
Why Attorneys Need Prior Acts Coverage Beyond Their State’s Statute of Limitations
Question from a Law Firm:
Our state has a two-year statute of limitations for legal malpractice claims. Why maintain an attorney malpractice insurance prior acts date that goes back more than two years?
Statutes of Limitations Do Not Eliminate the Need for Prior Acts Coverage
A two-year statute of limitations does not prevent clients from filing legal malpractice claims involving work performed years earlier. State laws contain exceptions extending the time available to file a malpractice lawsuit. These exceptions make maintaining attorney malpractice insurance prior acts coverage essential.
Why Legal Malpractice Claims May Arise Years Later
Circumstances impact when the statute of limitations begins or expires:
-
-
- Discovery Rule: Certain states start the limitations period when clients discover, or reasonably should have discovered, the alleged malpractice.
- Continuous Representation: Other states extend or toll the limitations period while an attorney continues representing the client in the same matter.
- Minors and Legal Disabilities: Certain states extend filing deadlines for minors or have qualifying legal disabilities.
- Fraudulent Concealment: An attorney’s error concealment extends the time available to file a claim.
- Different Causes of Action: Depending on state law, breach-of-contract and other claims may have different filing deadlines.
- Repose Statutes – States impose statutes of repose that establish an outside deadline.
-
ALFA International’s State-by-State Legal Malpractice Guide
ALFA International, a global network of independent law firms, published its 2024 Professional Liability Legal Malpractice Statutes of Limitation Guide. The guide compares state laws, including applicable limitations periods, discovery rules, continuous representation provisions, and other important exceptions.
Why Maintaining Your Prior Acts Date Matters
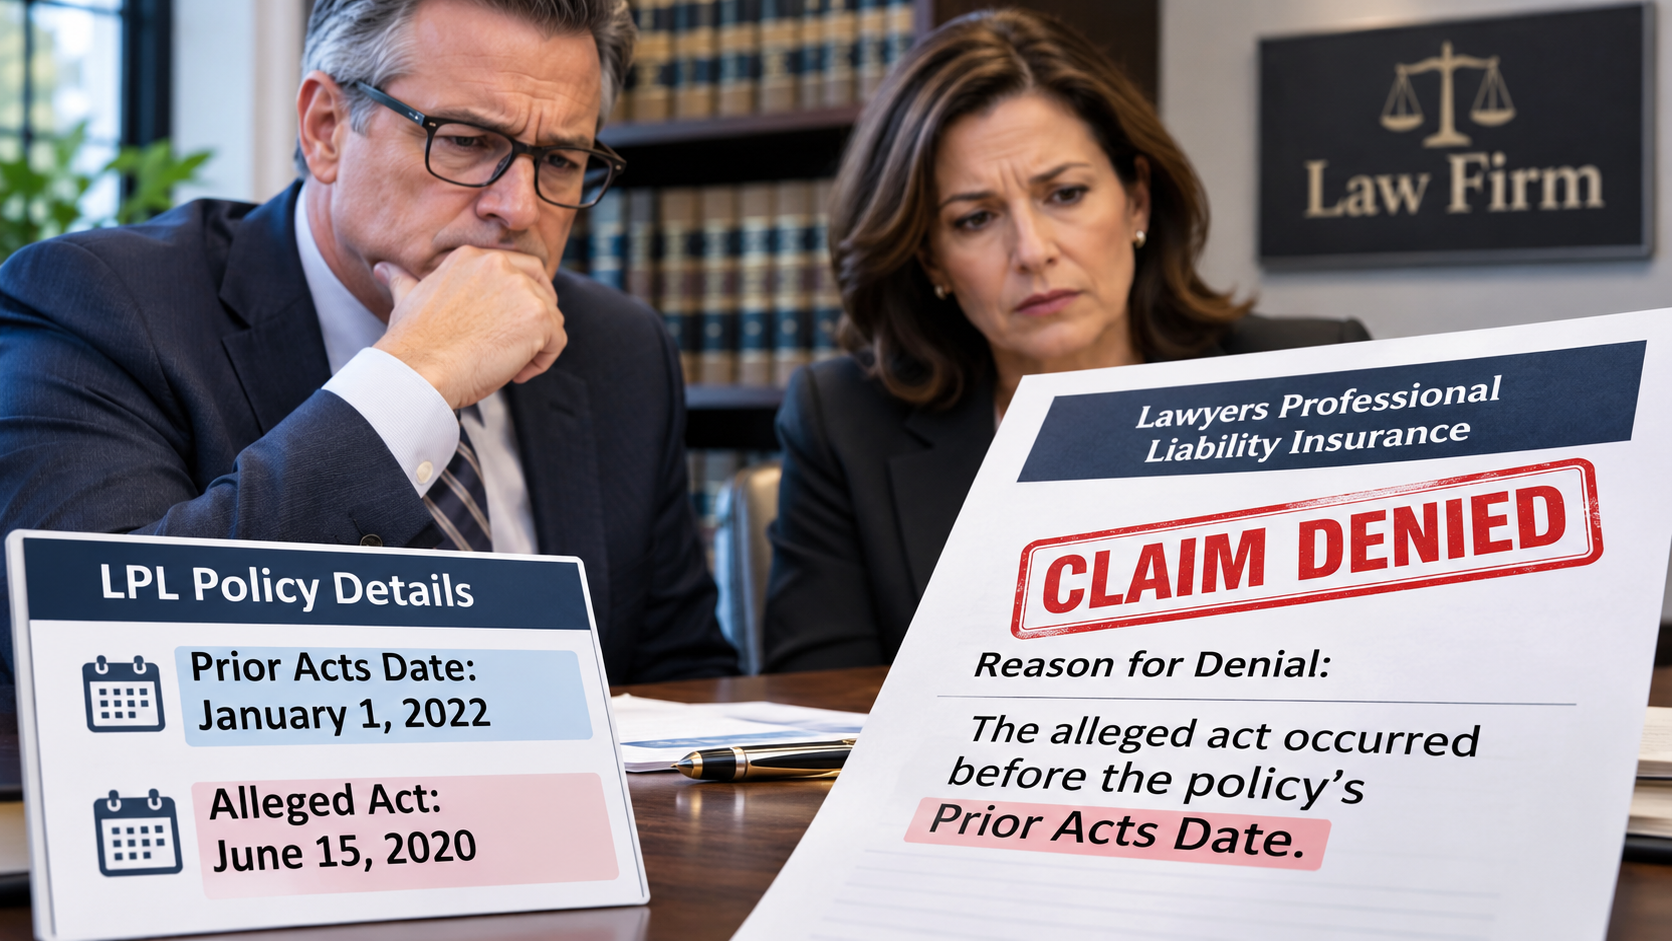
Lawyers Professional Liability (LPL) policies use claims-made coverage. Your policy’s prior acts date, also called its retroactive date, determines how far back your past acts coverage. For example, suppose your law firm established a January 1, 2020, prior acts date. In 2026, a former client alleges malpractice involving legal services performed in 2021. With a January 1, 2020, prior acts date your current policy responds. However, your prior acts date changed to January 1, 2024, your current insurer denies coverage because the alleged malpractice occurred before that date.
Attorney Malpractice coverage has two parts.
-
-
- Defense costs – For claims that go to trial average defense costs exceed $100,000.
- Indemnity costs – Depending on the matter indemnity payments could exceed $500,000.
-
A denied claims means the law firm not the insurer pays the claim.
Contact L Squared Insurance Agency to review your Lawyers Professional Liability insurance and ensure your policy provides the appropriate prior acts coverage.
Request a Legal Malpractice Quote
Contact Me Today
Lee Norcross, MBA, CPCU
California License # 0D87292
L Squared Insurance Agency, LLC ® DBA in California as L2 L Squared Insurance Agency, License # 0L93416
Managing Director, CEO
Lee@L2Ins.com
616-726-7080
Disclaimer: Statutes of limitations and insurance coverage depend on applicable state law, individual circumstances, and policy language. Consult qualified legal counsel regarding specific filing deadlines.