No Grace Period for Accountants Professional Liability Insurance Lapsed Coverage
Your Accountants Professional Liability Insurance expires Friday, but you are still waiting for another quote. Can you let your current policy expire and bind coverage after the weekend?
Do not count on it.
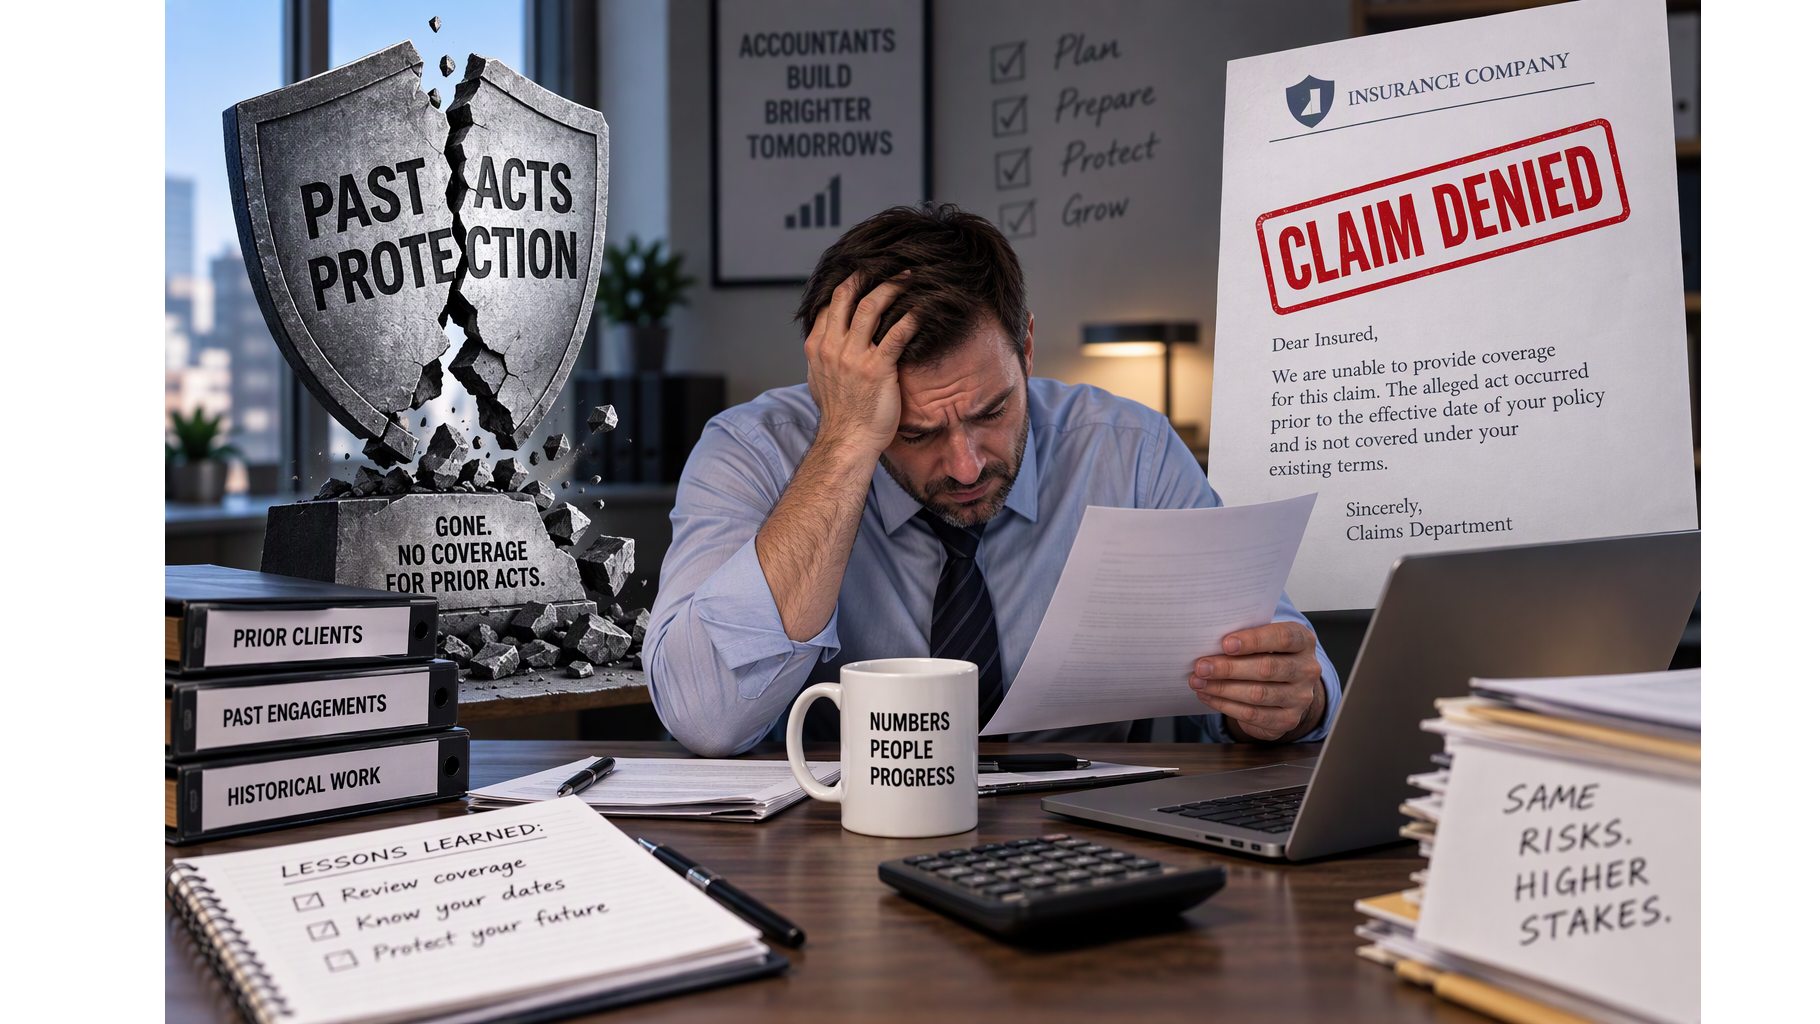
With claims-made Accountants Professional Liability Insurance continuous claims-made coverage matters. Allowing your policy to expire while shopping for coverage creates uninsured days or coverage gap. This jeopardizes protection for professional services performed years earlier.
The Coverage lost is more than a Couple of Days
It is easy to think of an insurance lapse as simply the time between two policies. With an occurrence policy form this is the correct assumption. If your existing policy expires Friday and a replacement policy starts Monday, you assume you only lost coverage for the weekend. With claims-made insurance, the consequences are greater.
Your existing policy prior-acts date protects professional services performed years earlier. With coverage gaps insurers refuse to protect past acts. Potentially years of past acts coverage is gone.
Protect Your Retroactive Date
The retroactive or prior-acts date establishes how far back a claims-made policy responds to covered professional acts. With claims-made coverage the policy inforce at the time the claim is made responds using the policy form currently inforce. If an alleged error occurred before the applicable retroactive date, the current policy provides no coverage even when the claim is made during the current policy period. Preserving continuous claims-made coverage with the appropriate retroactive date provides protection for past professional services. For an established accounting firm, that date represents years of prior professional work.
Do Not Assume an “Automatic” Extended Reporting Period is a Grace Period
When an Accountants Professional Liability policy provides an Automatic Extended Reporting Period (ERP) after coverage terminates. This does not cover ongoing work. It only covers work performed prior to the policy’s termination date. When Insurers refuse to match you expiring coverage’s prior acts date. After the Automatic ERP terminates so does your past acts coverage.
Firm Changes Also Create Coverage Issues
Pay particular attention to insurance when an accounting practice changes ownership, restructures, or merges into another entity.
Coverage written for an old entity does not necessarily extend to a new entity. Predecessor-firm coverage becomes important when a successor firm needs protection for professional services performed by its predecessor. Address this issue before terminating existing coverage.
Avoid Coverage Gaps
As expiration approaches:
-
-
- Start the renewal process early.
- Complete applications accurately.
- Respond promptly to underwriting requests.
- Verify your prior-acts or retroactive date.
- Review predecessor-firm coverage when applicable.
- Understand exactly how the Automatic ERP works.
- Report known claims and circumstances in the current policy term.
- Bind acceptable renewal or replacement coverage before your existing policy expires.
-
The Bottom Line: Protect Your Prior Acts
Claims involving past professional services frequently arise after the work was performed, making proper prior-acts protection vital. Potentially creating a coverage gap simply when waiting for one more quote might cause a loss of past acts protection. Protect continuous coverage first. Preserve your prior acts.
Accountants Professional Liability Insurance policies vary by insurer and policy form.
Get Accounting E&O Insurance Quote
Contact Me Today
Lee Norcross, MBA, CPCU
California License # 0D87292
L Squared Insurance Agency, LLC ® DBA in California as L2 L Squared Insurance Agency, License # 0L93416
Managing Director, CEO
Lee@L2Ins.com
616-726-7080