After a Malpractice Claim When Can a Law Firm Return to an Admitted Insurance Insurer?
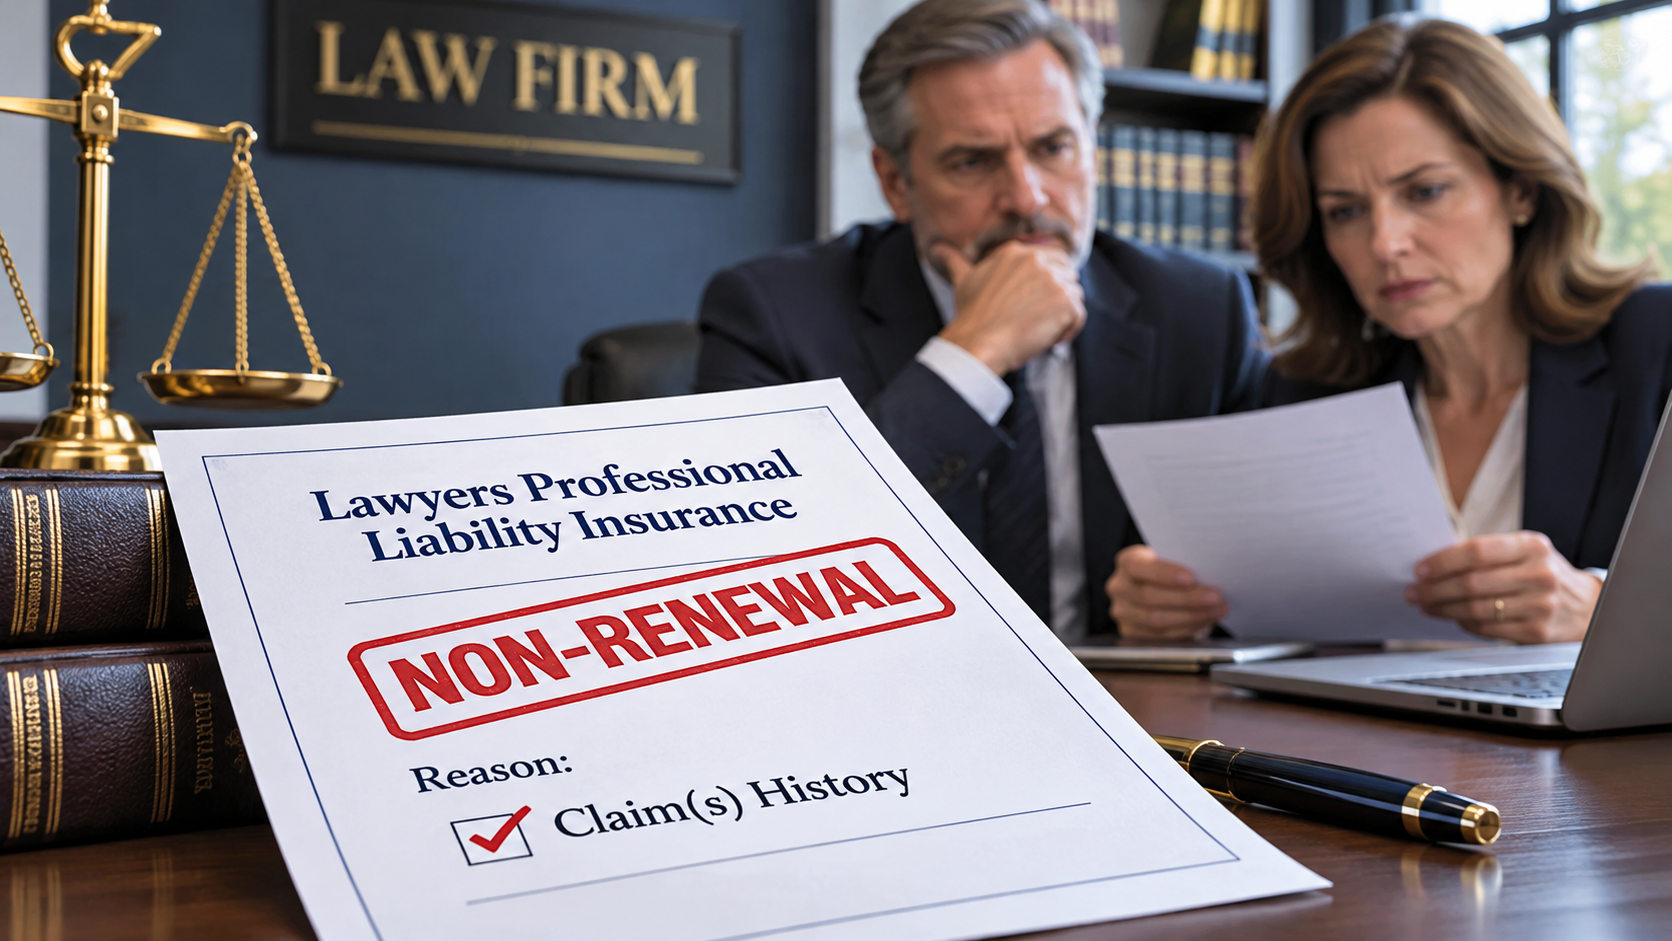
Legal malpractice claims impact a law firm’s ability to obtain affordable Lawyers Professional Liability Insurance (LPL). When an insurer non-renews coverage because of a claim(s), the firm purchases insurance from a surplus lines (non-admitted) insurer at a substantially higher premium.
Although no fixed waiting period exists, admitted LPL insurers prefer three to five years without additional malpractice claims activity. The type, severity, and frequency of previous claims directly impacts when a firm can return to the admitted market.
What Factors Affect a Law Firm’s Return to Admitted Insurance?
Insurance underwriters evaluate key factors when reviewing a law firm’s malpractice claims history:
-
-
- Claim Severity: Large settlements, significant defense costs, or unresolved claims make admitted coverage more difficult to obtain.
- Cause of the Claim: Claims involving missed deadlines, procedural errors, or poor client communication indicate preventable problems.
- Corrective Actions: Improving their calendaring systems, additional supervision, and/or risk management procedures help obtain admitted coverage sooner.
- Areas of Practice: Certain legal practice areas carry greater malpractice exposure, which limits available insurance options.
- Claims Frequency: Multiple malpractice claims, even without indemnity payments, extends the time a law firm remains in the surplus lines market.
-
Can a Law Firm Return to Admitted Coverage Sooner?
Yes. Demonstrating a malpractice claim resulted from an isolated incident and documenting meaningful corrective actions shortens the time in surplus lines. Underwriters view improvements favorably when evaluating future insurance applications.
How Can a Law Firm Improve Its Insurance Options?
Providing only the complaint from opposing counsel is a sure why to stay in the surplus lines market. Opposing counsels job is to put the attorney’s actions in the worst possible light. Take time to fully explain claim. If the claim was preventable explain steps taken to prevent similar claims in the future
The Bottom Line
Three to five years without additional malpractice claims is a common underwriting guideline, not a guarantee of admitted coverage. The severity of the claim, the firm’s claims frequency, and its corrective actions ultimately influence when admitted insurers reconsider providing LPL Insurance. If your law firm faces a malpractice insurance non-renewal or significantly higher premiums, L Squared Insurance Agency can help explore admitted and surplus lines insurance options.
Visit www.l2insuranceagency.com to learn more about your Lawyers Professional Liability Insurance options.
Get Lawyers Liability Insurance Malpractice Insurance Quote
Contact Me Today
Lee Norcross, MBA, CPCU
California License # 0D87292
L Squared Insurance Agency, LLC ® DBA in California as L2 L Squared Insurance Agency, License # 0L93416
Managing Director, CEO
Lee@L2Ins.com
616-726-7080