No Grace Period for Lawyers Professional Liability Insurance
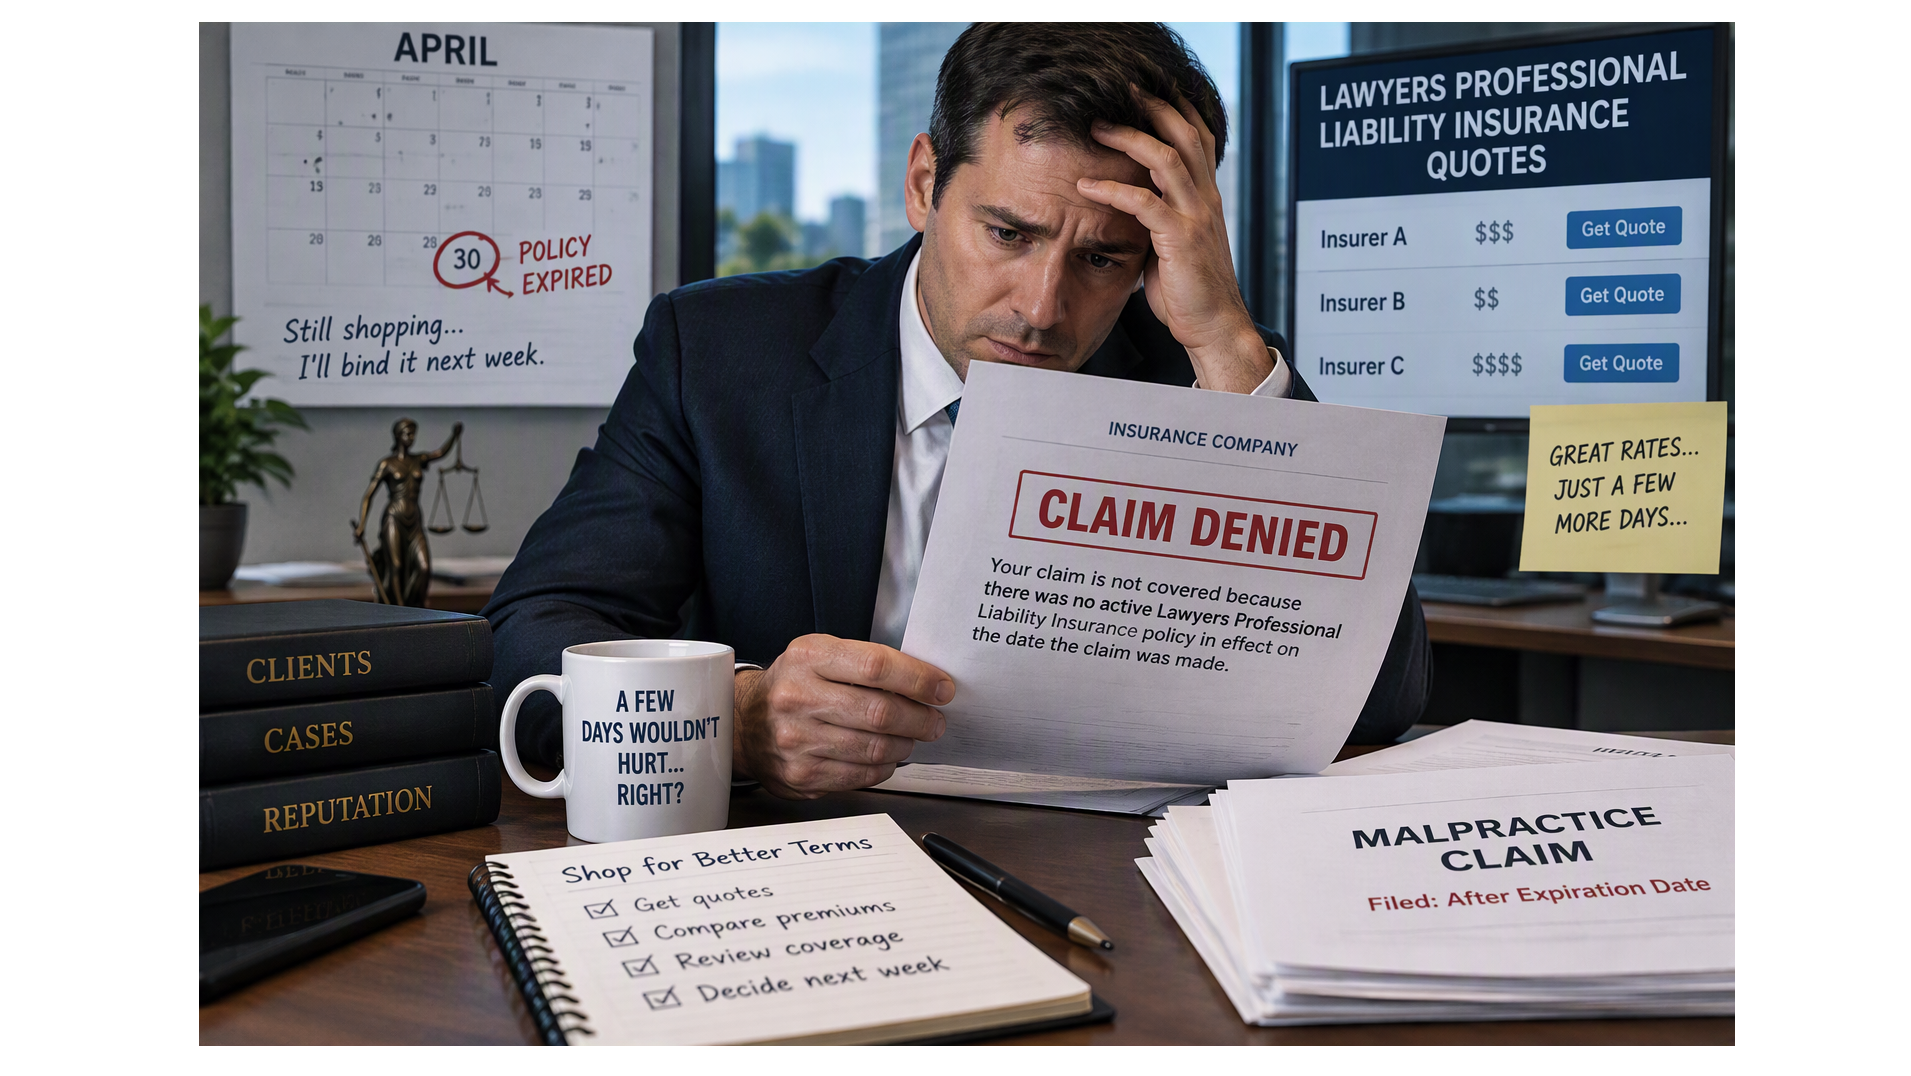
Your Lawyers Professional Liability Insurance policy expires tomorrow, but you are still waiting for other quotes.
Can you renew expired policies?
Do not count on it.
Treat the expiration date on a professional liability policy as a firm deadline. To maintain uninterrupted claims-made coverage, bind your renewal or replacement policy before your current policy expires.
Your Expiration Date Matters
With claims-made Lawyers Professional Liability Insurance continuous coverage matters. If your policy expires, do not assume your insurer will give you extra time to pay the premium, reinstate the policy, or backdate coverage. An insurer may agree to renew after expiration but never build your insurance strategy around that possibility. Bind your coverage before the expiration date.
Do not Risk a Coverage Gap While Shopping for a Better Quote
Reviewing malpractice insurance options at renewal by comparing insurers, premiums, and coverage makes sense. Letting your existing policy expire while you continue shopping does not.
Suppose your policy expires Friday, but you expect a competing quote on Monday. Waiting those few extra days seems harmless, but it is not worth the risk. A claim reported on Monday morning lacks coverage and the Monday quote excludes the claim. A coverage gap impacts prior-acts protection. Instead of risking a lapse to save money, make sure you have acceptable coverage bound before the existing policy expires. A lower premium is not a bargain if getting it jeopardizes your coverage.
An “Automatic” Extended Reporting Period Is Not a Grace Period
Do not confuse an “Automatic” Extended Reporting Period (ERP) with a grace period.
They are not the same.
An automatic ERP provides additional time to report claims arising from professional services performed during the applicable coverage period when no other insurance provides coverage. It does not keep the expired policy in force.
Always review the actual ERP provisions, deadlines, and conditions in your policy.
Do not Wait Until the Last Minute for Loss Runs
If you plan to shop your Lawyers Professional Liability Insurance, start early. Alternative insurers require applications, supplemental information and current loss runs before finalizing terms. Added information impacts an insurer’s willingness to offer coverage or the terms offered. Waiting until the final days before expiration leaves little room to solve problems.
Give yourself enough time to:
-
-
- Obtain current loss runs.
- Complete applications accurately.
- Respond to underwriting questions.
- Compare coverage as well as price.
- Verify your prior-acts or retroactive date.
- Bind coverage before your existing policy expires.
-
Switching Insurers? Protect Your Prior Acts
When changing professional liability insurers, do not focus only on premium.
Pay close attention to your prior-acts coverage and retroactive date.
Your law firm may have years, or even decades, of professional services that you want protected under your claims-made coverage. Do not jeopardize that protection simply because you waited too long to complete a renewal. Confirm the terms of the replacement policy before allowing the current policy to expire.
The Bottom Line: Do not Expect a Grace Period
Your Lawyers Professional Liability Insurance expiration date should trigger action, not another round of shopping.
If you are staying with your current insurer, bind the renewal before expiration.
If you are changing insurers, bind the replacement coverage before expiration.
And if you are still waiting for another quote as the deadline approaches, do not assume you can let your existing policy expire and fix the problem later.
Protect continuous claims-made coverage first. Shop for savings second.
Waiting for a better quote is not worth creating a potentially much bigger insurance problem.
Lawyers Professional Liability Insurance policies vary by insurer and policy form. Review your specific policy, endorsements, prior-acts or retroactive date, ERP provisions, and renewal terms to determine how coverage applies.
Get Lawyers Liability Insurance Malpractice Insurance Quote
Contact Me Today
Lee Norcross, MBA, CPCU
California License # 0D87292
L Squared Insurance Agency, LLC ® DBA in California as L2 L Squared Insurance Agency, License # 0L93416
Managing Director, CEO
Lee@L2Ins.com
616-726-7080